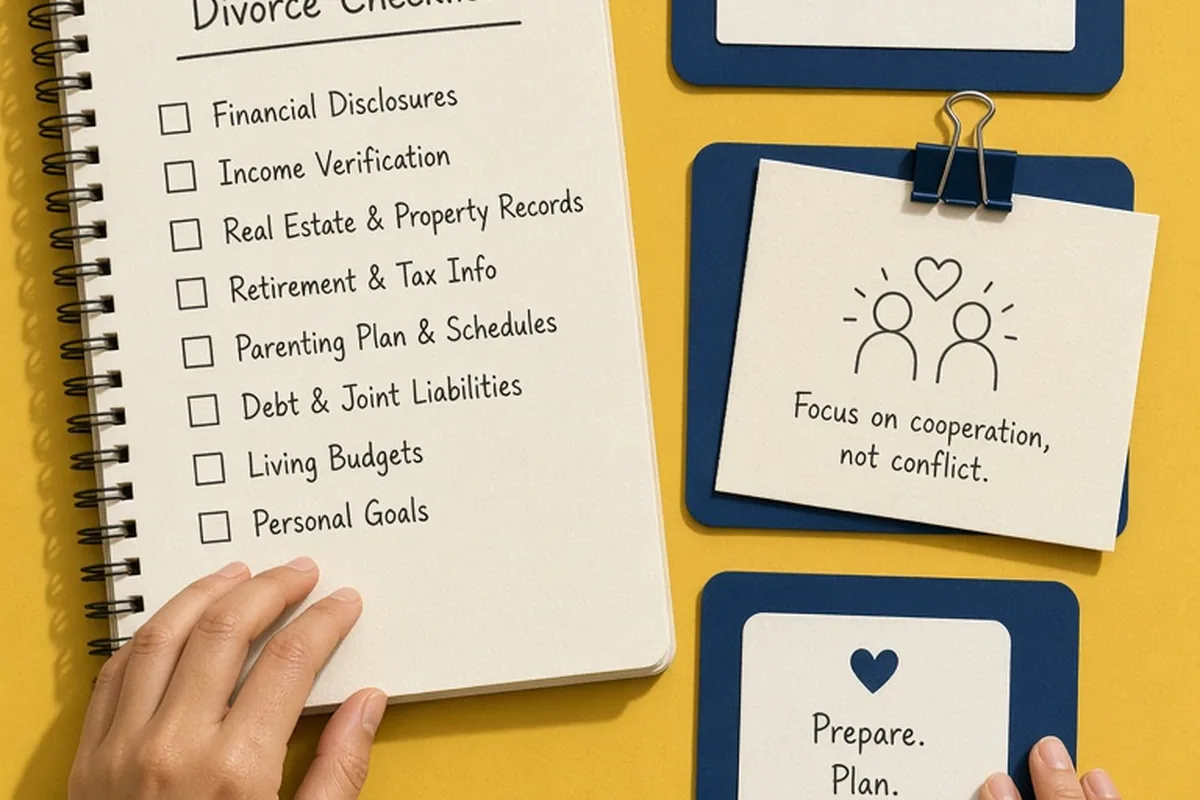
A mediation friendly divorce checklist organizes your financial records, parenting priorities, property documentation, and personal goals before negotiation sessions begin. Preparing complete disclosure packets, including tax returns, bank statements, retirement summaries, debt balances, and proposed daily routines for children, helps both spouses resolve issues cooperatively. This structured preparation minimizes administrative delays, reduces total mediation hours, and supports fair, durable agreements outside a courtroom setting.
Entering divorce mediation without organized records often leads to stalled discussions, emotional friction, and repeated session scheduling. Taking time to assemble financial disclosures, inventory marital assets, clarify parenting objectives, and define individual living budgets transforms an overwhelming legal transition into a structured, problem-solving process.
Financial Disclosure Documents and Income Verification
Transparent financial disclosure forms the backbone of any productive divorce mediation. Mediators cannot provide legal advice or compel discovery in the manner of a trial judge, which means the process relies on voluntary, accurate disclosure from both parties. Gathering complete income verification early prevents suspicion, reduces friction, and allows both spouses to negotiate from an identical set of verified facts. Missing or incomplete data inevitably forces the mediator to pause discussions, adding unnecessary session costs and administrative delay.
Begin by compiling personal and business tax returns, Form W-2s, 1099 statements, and year-to-date paystubs covering the past three to five years. If either spouse is self-employed, owns an interest in a business, or receives non-wage compensation such as bonuses, stock grants, or commissions, collect profit-and-loss statements, corporate balance sheets, and distribution records. Federal tax rules regarding filing status, dependency exemptions, and deductions change based on the timing and structure of your separation agreements, making full disclosure vital for long-term planning.
Further reading: IRS Publication 504: Divorced or Separated Individuals
Real Estate, Mortgages, and Personal Property Records
Housing decisions carry deep emotional weight and significant financial consequences. To facilitate clear discussions about whether to sell the marital residence, execute a buyout, or maintain joint ownership for an agreed period, spouses need an accurate picture of equity and ongoing carrying costs. You should obtain recent mortgage statements, home equity line of credit balances, annual property tax assessments, and current homeowners insurance policies. If refinancing is being considered, consulting a lender early provides realistic expectations about borrowing qualifications and prevailing interest rates.
Personal property, vehicles, and household contents also require thoughtful documentation. Rather than debating every household item during paid mediation hours, draft an inventory of high-value personal property, including vehicles, recreational equipment, jewelry, art, and valuable collections. Note title ownership, loan balances, and current estimated resale values. Minor household furnishings and everyday personal belongings are generally best divided independently between spouses using an itemized list, reserving formal mediation time for contested items or high-value physical assets.
Further reading: USA.gov: Get a copy of a divorce decree
Retirement Accounts, Pensions, and Tax Considerations
Retirement assets, such as defined contribution 401(k) plans, traditional individual retirement accounts, Roth accounts, and defined benefit pensions, represent a major share of marital wealth. Because these funds carry specific tax rules and withdrawal restrictions, their face value rarely reflects their actual after-tax spending power. Prepare for mediation by collecting the latest account summaries, plan description documents, vesting schedules, and pension benefit estimates.
Dividing workplace retirement plans typically requires a court order known as a Qualified Domestic Relations Order, or QDRO, depending on plan types and jurisdiction rules. Transferring funds incorrectly can trigger unintended income tax liabilities or early withdrawal penalties. Reviewing official tax guidelines regarding separation agreements ensures both parties understand how tax filing statuses, asset liquidations, and transfers incident to divorce affect future net income and retirement security.
Further reading: IRS Publication 504: Divorced or Separated Individuals
Parenting Plans, Child Custody, and Daily Schedules
When children are involved, mediation works best when parents shift the focus from theoretical custody labels to the practical realities of daily caregiving and stability. Drafting a workable parenting plan requires detailing regular weekly schedules, transportation logistics, school communication, extracurricular activity costs, and medical decision-making protocols. Bring school calendars, activity schedules, and records of current medical and child care expenses to your preparation sessions.
Consider approaching the parenting schedule with built-in flexibility for holidays, school vacations, birthdays, and travel. A mediation-friendly mindset focuses on the developmental needs of the children rather than rigid scorekeeping of parenting hours. Formulating two or three viable calendar options before meeting with the mediator helps parents explore compromises smoothly, avoiding deadlocks over minor scheduling adjustments.
Debt Obligations, Credit Cards, and Joint Liabilities
A complete division of marital property is impossible without an equally clear accounting of all outstanding debts. Lingering joint liabilities create ongoing risk for both credit scores if one party misses an assigned payment post-divorce. Collect current billing statements for all unsecured credit cards, student loans, auto financing agreements, medical debts, tax liens, and personal family loans. Clearly identify which accounts are held jointly and which are under individual names.
Mediation provides an environment to design practical debt settlement strategies, such as paying off balances from proceeds of an asset sale, transferring individual debt to separate balance-transfer cards, or refinancing vehicle loans to remove a co-signer. Spouses should obtain their individual credit reports prior to sessions to ensure no forgotten joint liabilities or open credit lines are omitted from the final settlement agreement.
Post-Divorce Budgets and Spousal Support Expectations
Transitioning from a single household budget to two separate residences requires realistic mathematical projections. Both spouses need to draft post-divorce monthly spending plans that reflect actual anticipated living expenses, including rent or mortgage, utilities, health insurance premiums, transportation, groceries, and personal savings. Unrealistic budget proposals often undermine support negotiations, creating unnecessary defensiveness during meetings.
When spousal maintenance or alimony is an issue, mediation allows parties to discuss support amounts and durations that reflect earning capacity, career pauses for caregiving, educational retraining needs, and long-term financial self-sufficiency. Because state statutes handle alimony guidelines differently, knowing your state's general statutory framework helps both spouses evaluate reasonable financial compromise without expecting unreasonable outcomes.
Further reading: USA.gov: Get a copy of a divorce decree
Mediation Ground Rules and Document Organization Strategy
The physical and digital organization of your paperwork directly impacts how smoothly your mediation sessions progress. Create a secure, shared digital folder or indexed physical binder organized into clear sections: income, banking, real estate, investments, debts, insurance, and parenting. Giving the mediator and both parties identical access to organized records eliminates confusion over conflicting document versions and keeps the conversation focused on practical solutions.
Equally important is committing to constructive communication ground rules. Mediation requires listening without interruption, refraining from personal accusations, and focusing on forward-looking agreements rather than past grievances. Establishing an agreed agenda for each meeting allows spouses to tackle straightforward asset items first, building collaborative momentum before addressing more complex custody or support topics.
Illustrative Scenarios
Resolving Home Equity and Refinance Uncertainty
During an initial mediation session, Jordan and Alex reached an impasse over the family home. Jordan wanted to keep the property, while Alex insisted on an immediate listing, fearing Jordan could not qualify for a mortgage buyout and that market conditions might shift. Instead of continuing an abstract argument, the mediator directed them to pause the session and gather objective data. Jordan met with a mortgage professional to secure a formal pre-approval letter for a refinance, while Alex obtained an independent home valuation. With concrete numbers in hand at the next session, both parties agreed on a ninety-day refinance deadline with an automatic listing contingency if financing fell through.
Key point: Replacing subjective assumptions with verified lender terms and official appraisals prevents deadlock and allows spouses to craft realistic financial options.
Structuring an Unbalanced Holiday Parenting Calendar
Taylor and Morgan struggled to divide major winter holidays for their elementary-aged children, resulting in tense discussions during their first mediation appointment. Both parents wanted traditional Thanksgiving and winter break dates every year, leading to competing proposals that felt unfair to each side. Rather than disputing past family traditions, they focused on their children's actual school vacation windows and created an alternating-year framework. They mapped out odd and even calendar years for major holidays and established set hours for local family dinners on extended weekends.
Key point: Drafting multi-year alternating schedules grounded in the child's academic calendar eliminates recurring holiday disputes and provides predictable planning for both homes.
Frequently asked questions
What documents should I gather first before scheduling a divorce mediation session?
Start by compiling three years of federal and state tax returns, recent paystubs, statements for all active bank and investment accounts, mortgage documents, credit card bills, and retirement plan summaries. Having these core financial records organized establishes an objective baseline for all property and support discussions.
How do state laws affect the divorce mediation process?
Divorce procedures, property division principles (community property versus equitable distribution), child support formulas, and filing requirements are governed by state and local authorities. While mediation gives spouses flexibility to craft custom agreements, any final settlement must meet statutory standards before a judge approves the decree.
Can we still use mediation if we have not agreed on child custody or support?
Yes. Mediation is designed specifically to help parents resolve unresolved parenting schedules, decision-making responsibilities, and child support calculations. Bringing school calendars, caregiving schedules, and clear expense histories allows the mediator to guide you toward a balanced parenting plan.
Are mediation agreements legally binding once signed?
A signed memorandum of understanding drafted in mediation serves as the blueprint for your final marital settlement agreement. Once formalized into legal documents and approved by the court, the agreement becomes part of the enforceable divorce decree.
Your next step
Download or compile your three most recent years of tax returns, bank statements, and debt summaries into a single indexed binder to prepare for your initial mediation consultation.