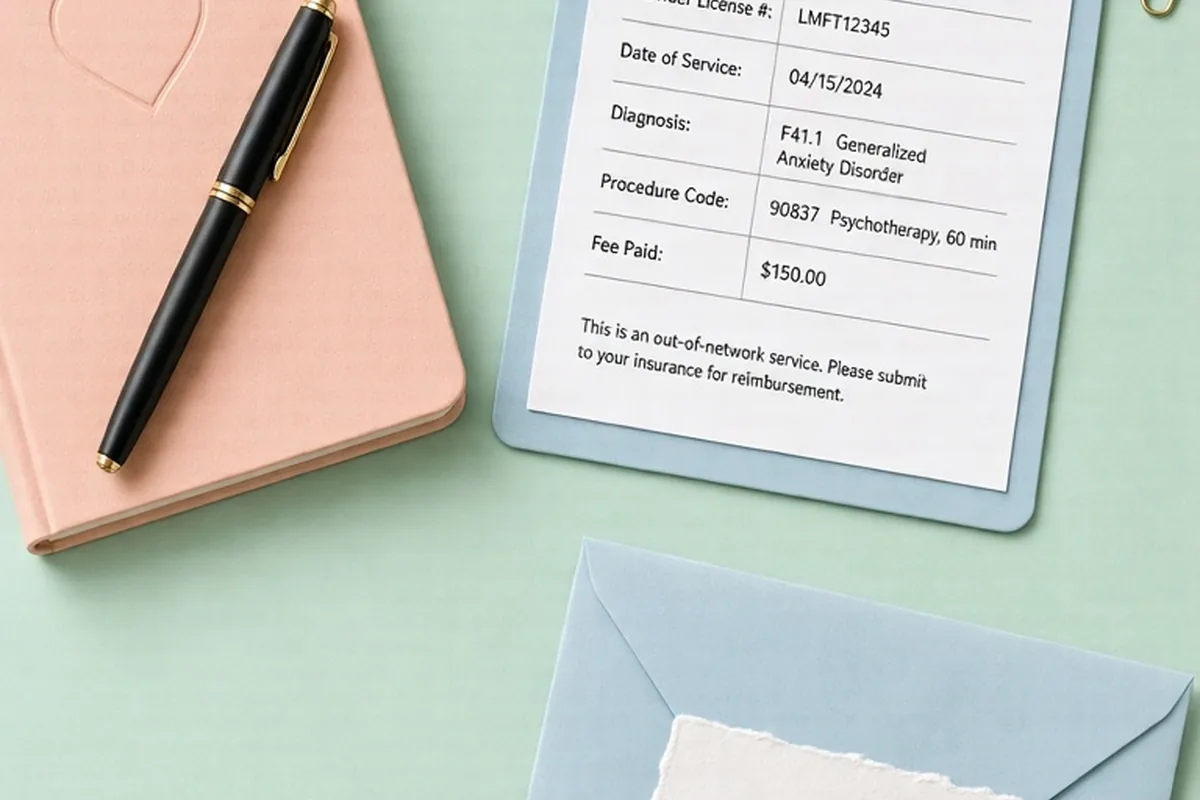
A superbill is an itemized document created by an out-of-network mental health provider that details the services you received, diagnostic codes, procedure codes, and the fees you paid out of pocket. You submit this document directly to your health insurance company to request partial reimbursement under your plan's out-of-network behavioral health benefits, subject to your deductible and plan rules.
Navigating mental healthcare often requires balancing clinical fit with financial reality. Many licensed therapists operate as out-of-network providers, meaning they collect fees directly from clients rather than billing insurance plans. Understanding how superbills function helps you pursue reimbursement efficiently while budgeting for continuous care.
Anatomy of a Therapy Superbill and How Insurers Read It
A superbill serves as a specialized receipt that translates a psychotherapy session into standardized medical billing language. Unlike a standard credit card receipt or basic invoice, a superbill contains exact clinical identifiers that an insurance claims department requires to evaluate medical necessity. Without these specific elements, claims examiners will reject reimbursement requests outright.
Every compliant superbill includes your identifying information, the provider's identifying details, and clinical coding. The provider details must feature their full legal name, professional license type, National Provider Identifier (NPI), and federal Tax Identification Number (TIN) or Employer Identification Number (EIN). The physical office address where the service occurred is also required, along with a statement indicating that the client has paid the charge in full.
The clinical section pairs standard diagnostic codes with procedure codes. Diagnostic codes, drawn from the International Classification of Diseases (ICD), indicate the clinical condition being addressed, such as generalized anxiety or major depressive disorder. Procedure codes, known as Current Procedural Terminology (CPT) codes, describe the exact nature and duration of the session, such as individual psychotherapy, initial intake assessments, or family sessions. Insurers evaluate these pairings to determine whether the treatment matches their coverage guidelines.
Further reading: NIMH: Psychotherapies
Understanding Out-of-Network Insurance Mechanics and Benefit Rules
Health insurance plans treat out-of-network behavioral health services differently than in-network care. Under an in-network arrangement, a provider agrees to contracted rates directly with your insurer. With out-of-network care, you pay the therapist's full session fee upfront, submit the superbill, and wait for your insurer to process the claim according to your policy's out-of-network schedule.
Reimbursement generally depends on your out-of-network deductible, which is often distinct from and higher than your in-network deductible. Until your total qualifying out-of-pocket medical spending reaches this out-of-network deductible threshold, your insurer will apply approved superbill amounts toward satisfying your deductible rather than sending you cash reimbursement. Once the deductible is met, the plan reimburses a set coinsurance portion of the allowable amount.
The allowable amount—sometimes termed the usual, customary, and reasonable (UCR) fee—represents the maximum dollar figure your insurer deems appropriate for a specific service in your geographic region. If your therapist charges a session rate higher than the insurer's allowable amount, the insurance company calculates reimbursement based solely on their internal cap, leaving you responsible for the remaining difference. Marketplace and commercial plans vary widely in how they structure these deductibles, copayments, and allowable caps.
Prior authorization requirements present another critical insurance barrier. Certain plans mandate pre-approval or a formal referral before they will reimburse psychotherapy sessions, especially for extended appointments, specialized treatment modalities, or intensive outpatient programs. Failing to secure necessary authorizations before receiving care can lead to claim denials regardless of medical necessity.
Further reading: HealthCare.gov: Mental health coverage
Step-by-Step Submission Process for Superbill Reimbursement
Filing a superbill requires thorough record-keeping and adherence to your insurer's specific submission protocols. Most health insurance companies offer an online member portal or mobile application where you can upload digital copies of your claims. Alternatively, insurers accept claims submitted by postal mail using a standard CMS-1500 or specialized member claim form available on their websites.
Begin by requesting your superbill from your therapist at a regular cadence, typically at the end of each calendar month or after each completed appointment block. Review the document carefully to verify that your full legal name, date of birth, and policy number match your insurance records perfectly. Minor discrepancies, such as misspelled names or transposed digits in an identification number, represent frequent causes of administrative processing delays.
Attach the completed member claim form to your superbill, ensuring you designate yourself as the payee rather than the provider, since you have already paid the provider in full. Keep personal digital copies of every document you submit, including date stamps, transaction confirmations, and communication records. Once submitted, monitor your member account for the generated Explanation of Benefits (EOB), which outlines the billed amount, the approved allowable amount, the portion applied to your deductible, and any issued payment.
Common Superbill Denial Reasons and How to Resolve Them
Claim denials are common in out-of-network claims administration, but many denials stem from correctable administrative errors. A frequent reason for rejection is an incorrect place of service code, particularly for telehealth sessions. Virtual appointments require specific modifier codes and place-of-service indicators; if a therapist bills a virtual session using an in-person office code without the required telehealth modifier, the insurer may reject the claim automatically.
Another primary hurdle involves diagnostic exclusions or non-covered codes. Some insurance policies exclude specific diagnostic categories, such as adjustment disorders, relationship counseling without an identified individual psychiatric diagnosis, or developmental assessments. If a claim is denied for lack of medical necessity or non-covered status, contact your insurer to identify the exact rejection code listed on your Explanation of Benefits.
When an error originates on the document itself, ask your therapist to issue a corrected superbill clearly labeled with the appropriate revision indicators. Once received, submit the corrected document along with a formal appeal letter referencing the original claim number. If your insurer denies coverage due to administrative ambiguity or disputed allowable rates, you have the right to request a formal internal appeal, providing clinical justification letters from your clinician when necessary.
Further reading: NIMH: Psychotherapies
Alternative Lower-Cost Channels When Reimbursement Is Inadequate
When out-of-network insurance reimbursement is insufficient, unavailable, or restricted by high deductibles, alternative care pathways can help manage ongoing mental health expenses. Many individuals combine various direct-pay options, subsidized programs, and specialized tax-advantaged tools to maintain consistent clinical care without facing severe financial strain.
Sliding-scale slots represent one of the most accessible self-pay avenues. Many private-practice therapists reserve a portion of their caseload for clients experiencing financial limitations, adjusting their standard hourly rate based on household income and personal circumstances. Discussing sliding-scale availability directly during an initial consultation can significantly reduce out-of-pocket costs without involving insurance claims at all.
University-affiliated psychological clinics and training institutes provide another high-quality, reduced-cost option. In these settings, advanced graduate clinicians deliver evidence-based therapy under the direct supervision of licensed, experienced mental health faculty. These clinics often utilize income-adjusted payment structures, providing comprehensive individual and group therapy services at rates far below average private-practice fees.
Community mental health centers and non-profit provider collectives also deliver essential behavioral health services funded through local, state, or charitable grants. Furthermore, individuals with employer-sponsored Flexible Spending Accounts (FSA) or Health Savings Accounts (HSA) can pay for qualified psychotherapy sessions and out-of-network deductibles using pre-tax funds, effectively reducing the net financial burden regardless of insurance claim outcomes.
Further reading: NIMH: Psychotherapies
Further reading: HealthCare.gov: Mental health coverage
Verification Checklist: Key Inquiries for Your Health Plan Representative
Before beginning treatment with an out-of-network mental health provider, call the member services number on the back of your insurance card to verify exact policy limitations. Customer service representatives can clarify whether your specific plan includes out-of-network behavioral health coverage, as some restricted network plans, such as certain HMOs, provide zero out-of-network coverage outside of emergency stabilization.
Ask specific questions regarding your out-of-network deductible balance and whether mental health claims accumulate toward a shared deductible or a separate behavioral health deductible. Inquire about the maximum allowable amount for specific CPT codes, such as standard individual psychotherapy sessions, and ask whether virtual telehealth sessions are covered at the same rate as in-person appointments.
Finally, determine whether prior authorization, a primary care physician referral, or a formal treatment plan submission is required prior to your initial session. Note the representative's name, the date and time of the call, and a unique call reference number. Having documented proof of your pre-treatment verification provides critical leverage if claims are improperly processed or disputed later.
Further reading: HealthCare.gov: Mental health coverage
Illustrative Scenarios
Resolving a Telehealth Coding Rejection
Jordan began seeing an out-of-network psychotherapist for weekly video sessions and submitted monthly superbills to insurance. The insurer repeatedly rejected the claims, stating the service location was invalid. Jordan initially assumed the policy completely excluded virtual mental health care. After calling member services, Jordan discovered the therapist had listed an in-person office code without the mandatory telehealth location modifier. Jordan requested an updated superbill with the correct virtual service modifiers, resubmitted the claim through the online portal, and the insurer applied the approved fees toward the annual out-of-network deductible.
Key point: Billing errors frequently stem from missing place-of-service modifiers rather than policy coverage exclusions.
Managing High Deductible Expectations
Elena chose an out-of-network therapist and submitted superbills expecting immediate cash reimbursement checks. When the Explanation of Benefits arrived showing no reimbursement payout, Elena felt discouraged and considered stopping treatment. Reviewing the statement revealed that the entire approved amount had been credited toward an unmet out-of-network deductible. Recognizing that direct reimbursement would only begin after satisfying that annual threshold, Elena used a pre-tax Health Savings Account to cover session fees in the interim while budgeting for long-term care.
Key point: Out-of-network insurance benefits only yield direct reimbursements after the policy deductible is fully satisfied.
Frequently asked questions
Can I submit a superbill if I have an HMO insurance plan?
Most HMO plans do not provide out-of-network benefits unless an exception is granted or services involve emergency medical care. Review your specific summary of benefits and coverage or contact your plan representative to confirm whether your HMO policy offers any out-of-network mental health allowances.
How long do I have to submit a superbill after a therapy session?
Timely filing limits vary widely depending on the insurance carrier and policy contract, typically ranging from ninety days to one full calendar year from the date of service. Check your plan guidelines promptly to ensure your claims are submitted well before your insurer's filing deadline expires.
Why did my insurance company reimburse less than the total fee I paid?
Insurers calculate out-of-network reimbursements based on their internal allowable rate rather than the therapist's actual retail rate. If your therapist's fee exceeds the allowable rate, or if you have an unmet deductible or coinsurance percentage, your direct reimbursement will be lower than your out-of-pocket payment.
Can couples therapy be reimbursed using a superbill?
Reimbursement for couples therapy depends on your insurance policy's specific clinical coverage rules. Insurers generally require an established diagnostic code indicating that treatment addresses an individual partner's diagnosed mental health condition rather than general relationship counseling.
Your next step
Call your health insurance member services department today and use the verification checklist to confirm your exact out-of-network deductible, allowable CPT code rates, and submission guidelines before your next therapy appointment.