Affordable divorce options depend on your level of mutual agreement and household income. When spouses agree on major terms, filing an uncontested divorce pro se or using court fee waivers offers the lowest out-of-pocket cost. When minor disagreements remain, private mediation or unbundled legal services—where an attorney reviews specific documents rather than managing the entire case—provide professional guidance while preventing unpredictable retainer fees and protracted court litigation.
Ending a marriage is emotionally demanding, but the fear of overwhelming legal expenses often creates paralyzing uncertainty. When savings are minimal or household income barely covers current living costs, traditional litigation with open-ended retainer fees is simply out of reach. Understanding the spectrum of low-cost legal pathways allows both spouses to preserve their financial stability, maintain respectful boundaries, and reach a fair resolution without unnecessary debt.
Evaluating Pro Se Filing, Mediation, and Unbundled Legal Help
The most affordable path to divorce depends on whether you and your spouse can communicate productively about property, debts, and parenting. A pro se divorce, where both parties represent themselves without formal attorney appearances, carries the lowest price tag. This approach works best when there are few shared assets, no contested custody issues, and a shared commitment to completing administrative paperwork accurately. Local county clerk offices and state judicial websites frequently provide standardized forms and instruction packets specifically designed for self-represented litigants.
When couples agree on the broad outcome but struggle with specific calculations or logistical details, professional mediation bridges the gap without litigation costs. In mediation, a neutral third party guides discussions on asset splits, parenting time, and spousal support, helping both parties draft a memorandum of understanding. Because the mediator does not represent either person in court, the total expense is shared between the spouses and is generally a fraction of dual legal retainers.
For complex clauses such as retirement division or business interests, unbundled legal services—also known as limited-scope representation—offer a targeted middle ground. Instead of paying thousands of dollars for an attorney to handle every phone call and filing, you hire a lawyer for a fixed fee to review a draft agreement, calculate statutory child support formulas, or coach you before a hearing. This approach gives you targeted legal protection without continuous billing.
Requesting Court Fee Waivers and Accessing Local Legal Aid
Even when representing yourself, mandatory court filing fees, service of process costs, and administrative surcharges can strain an already tight budget. Most state and county court systems offer an application known as an In Forma Pauperis petition or a civil fee waiver. If your household income falls below a specific threshold determined by your state, or if you receive certain government assistance benefits, the court can waive initial filing fees, motion fees, and sometimes required parenting seminar costs entirely.
Applying for a fee waiver requires complete and verifiable financial transparency. You will need to submit documentation such as recent pay stubs, tax returns, proof of government assistance, or an itemized breakdown of mandatory monthly living expenses. Courts review these requests carefully to verify financial hardship. It is advisable to obtain your local court clerk's specific fee waiver application before submitting your initial divorce petition, as requesting the waiver at the time of filing prevents unexpected upfront charges.
If you do not qualify for a complete waiver but still cannot afford private representation, community legal aid organizations and volunteer lawyer projects can provide essential support. Many bar associations host periodic low-income legal clinics where volunteer family law attorneys offer free document reviews or procedural advice. While legal aid programs often have waiting lists and income eligibility caps, contacting them early in the separation process helps you identify available community resources.
Dividing Debts and Modest Assets Without Costly Appraisers
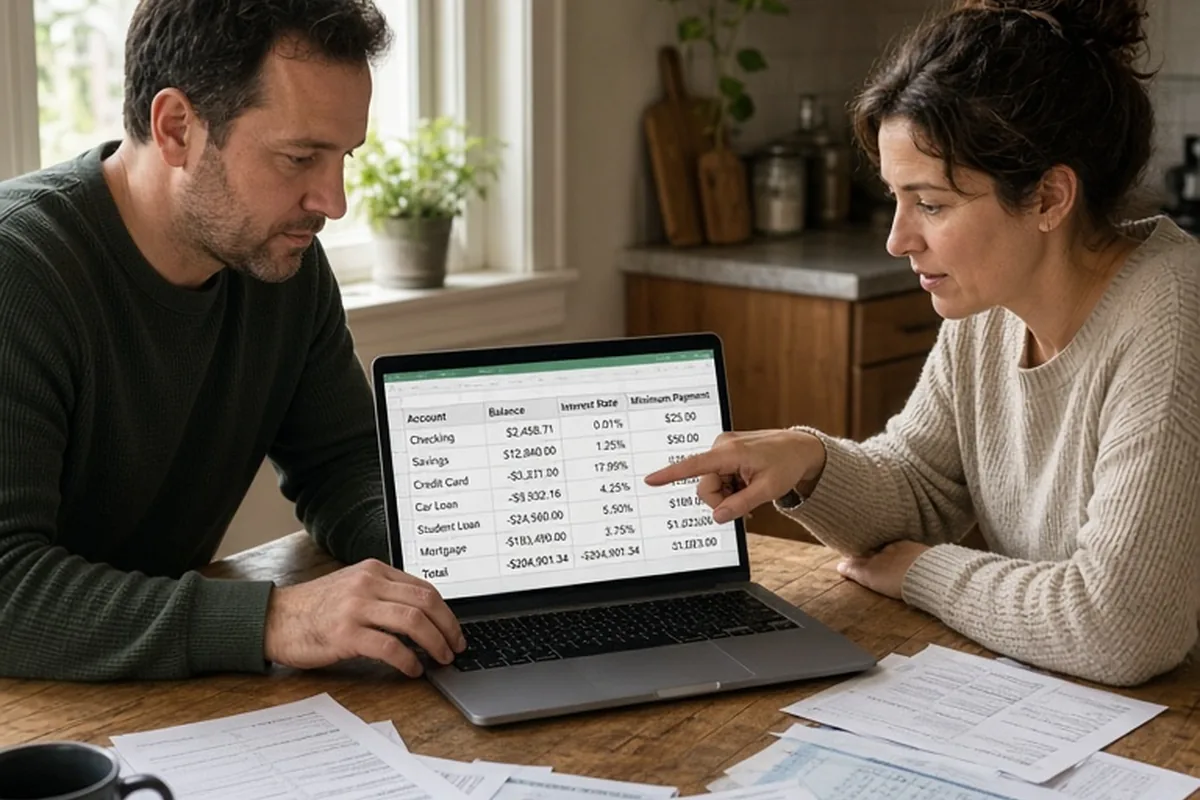
Disputes over property division frequently escalate divorce costs, especially when parties hire independent evaluators to value personal property. For couples with modest estates, creating a shared, transparent inventory of all assets and liabilities is the most cost-effective first step. Gather recent statements for bank accounts, auto loans, credit cards, and personal loans, organizing them into a single clear document that shows current balances and account ownership.
Dividing everyday household items rarely justifies professional appraisals. Instead of spending legal fees debating the value of furniture, electronics, or appliances, spouses can use fair market value based on current second-hand prices rather than original purchase costs. A practical method is using alternating selections or grouping items into two balanced packages and letting the other spouse choose first. This keeps negotiations practical and removes the financial burden of formal valuations.
Handling marital debt requires particular caution because creditors are not bound by your family court decree. If a joint credit card is assigned to one spouse in the settlement but remains open, the other spouse remains liable to the creditor if payments lapse. When funds are limited, prioritize closing joint accounts, transferring balances to individual cards where possible, or agreeing to allocate a specific tax refund or asset sale directly toward extinguishing shared consumer debt before finalization.
Building an Affordable Parenting Plan and Calculating Support
Parenting schedules and child support can become intense areas of conflict, but relying on court trials to establish a schedule drains family savings that are better spent on the children. Most jurisdictions provide free, publicly accessible child support calculation worksheets that use standardized statutory formulas based on parental incomes, health insurance costs, and the percentage of overnight parenting time. Running these numbers together transparently prevents unrealistic expectations and reduces contentious negotiations.
A practical parenting plan clearly defines regular weekly schedules, holiday rotations, school vacation sharing, and transportation responsibilities. Anticipating predictable recurring expenses—such as school supplies, sports fees, uninsured medical care, and child care—and establishing a straightforward method for sharing these costs prevents future enforcement hearings. Many parents successfully establish a dedicated joint checking account or use free expense-tracking apps where both parents log receipts and settle balances monthly.
When minor scheduling disagreements arise, agreeing ahead of time to use a community mediation service or a single consultation with a family counselor can resolve deadlocks before they require formal motions. Keeping the focus on the child's daily routine, stability, and emotional security allows both parents to create durable agreements without paying thousands in litigation fees.
Managing Living Costs and Cash Flow During the Separation Phase
Transitioning from a single household to two separate residences immediately increases everyday expenses like rent, utilities, and grocery bills. During the initial separation phase, establishing a temporary, written financial agreement helps prevent missed payments or sudden utility cutoffs. This informal or stipulated interim agreement should outline who pays specific household bills, how vehicle insurance is maintained, and how day-to-day child expenses are handled while the divorce is pending.
Protecting your individual credit profile is essential when navigating financial constraints. If both spouses have access to a shared line of credit, mutually agreeing in writing to freeze or restrict the account prevents unexpected charges that neither party can afford to repay. Opening an individual checking and savings account at a financial institution separate from your joint bank helps ensure that your earnings remain accessible for your immediate living needs.
Careful budgeting during this interim stage also reduces panic and prevents hasty settlement decisions driven by short-term cash crunches. Look for practical opportunities to reduce overhead, such as temporarily pausing discretionary subscriptions, shopping around for competitive auto insurance rates, and confirming whether you qualify for income-based utility assistance programs in your area.
Common Administrative Pitfalls That Increase Pro Se Costs
While self-filing is economical, procedural errors can cause delays, multiple court appearances, and additional administrative fees. A common mistake is using outdated court forms or failing to follow local statutory rules regarding service of process. Serving divorce paperwork must strictly adhere to state law—whether through a formal acceptance of service signed by your spouse, certified mail, or a professional process server—to ensure the court maintains proper jurisdiction.
Another frequent pitfall involves vague language in settlement agreements regarding timelines. Stating that an asset will be sold or a loan refinanced 'as soon as possible' frequently leads to disputes if one party delays for months. Writing precise, enforceable deadlines—such as specifying a thirty-day window to apply for refinancing or defining how listing price reductions will occur on a shared property—protects both spouses and avoids costly post-decree enforcement motions.
Finally, failing to prepare necessary ancillary documents, such as Qualified Domestic Relations Orders (QDROs) for employer retirement plans or vehicle title transfer affidavits, can result in hidden costs after the divorce is finalized. Before submitting your final decree to the judge, consult free self-help resources at your local court or invest in a one-hour unbundled legal review to confirm that all required forms are complete and properly executed.
Illustrative Scenarios
Resolving Joint Credit Card Debt on a Constrained Budget
Marcus and Elena decided to separate while carrying significant shared credit card debt and minimal savings. Elena initially assumed they would need expensive litigators to assign responsibility for the balances, which felt impossible given their tight finances. Marcus suggested listing every balance, interest rate, and monthly minimum payment in a shared spreadsheet. They realized that paying attorneys would cost more than their total combined debt. Instead, they agreed to sell a second vehicle with positive equity, pay off the highest-interest card, and split the remaining balance equally by opening separate individual balance-transfer cards. They presented their finalized, balanced agreement directly to the court without hiring adversarial representation.
Key point: Transparent financial disclosure and practical debt resolution between spouses can eliminate the need for costly contested court hearings.
Using Limited-Scope Review to Protect Parenting Time
Sarah and David agreed on an amicable divorce and planned to file all paperwork pro se to save money. However, Sarah felt uncertain about the legal phrasing of their shared custody schedule and holiday rotation, worrying that misunderstandings down the road might force them into court. Rather than retaining an attorney for full representation, Sarah hired a family lawyer for two hours of limited-scope consultation to review their self-drafted parenting plan. The lawyer suggested minor wording adjustments regarding pick-up locations and tax exemption rotation. Sarah and David incorporated the changes and filed their uncontested petition smoothly, saving thousands in retainer fees while gaining legal peace of mind.
Key point: Targeted, limited-scope document reviews offer affordable professional protection without the high cost of full representation.
Frequently asked questions
What happens if my spouse refuses to cooperate with an uncontested divorce?
If your spouse refuses to sign paperwork or negotiate terms, you can still file a petition for divorce on your own. You will need to serve the documents formally through court-approved methods, after which your spouse must respond within a statutory deadline. If they fail to respond, the court may allow you to proceed by default, though local self-help clinics can guide you through the required default forms.
Can I get a divorce if neither of us has money for an attorney retainer?
Yes. Couples with limited funds routinely complete their divorces through self-representation (pro se) using court-provided forms. You can also apply for an in forma pauperis fee waiver to eliminate court filing costs, and utilize community mediation or legal aid clinics for low-cost guidance.
How do we divide retirement accounts without paying high professional fees?
Basic individual retirement accounts (IRAs) can often be divided using a standard court order and transfer form provided directly by the financial custodian. However, employer-sponsored plans like 401(k)s require a Qualified Domestic Relations Order (QDRO), which is often handled most affordably through dedicated QDRO preparation services rather than full-service litigation attorneys.
Will filing without an attorney put me at risk of getting an unfair child support amount?
State child support calculations are determined by statutory guidelines and mathematical formulas rather than legal persuasion. By using your state's official child support worksheet and entering verified income, health insurance premiums, and overnight totals, you can calculate the exact statutory support amount without paying an attorney to run the figures.
Your next step
Download your local court's uncontested divorce packet and fee waiver application today, and organize your monthly income and debt statements in a single shared file.